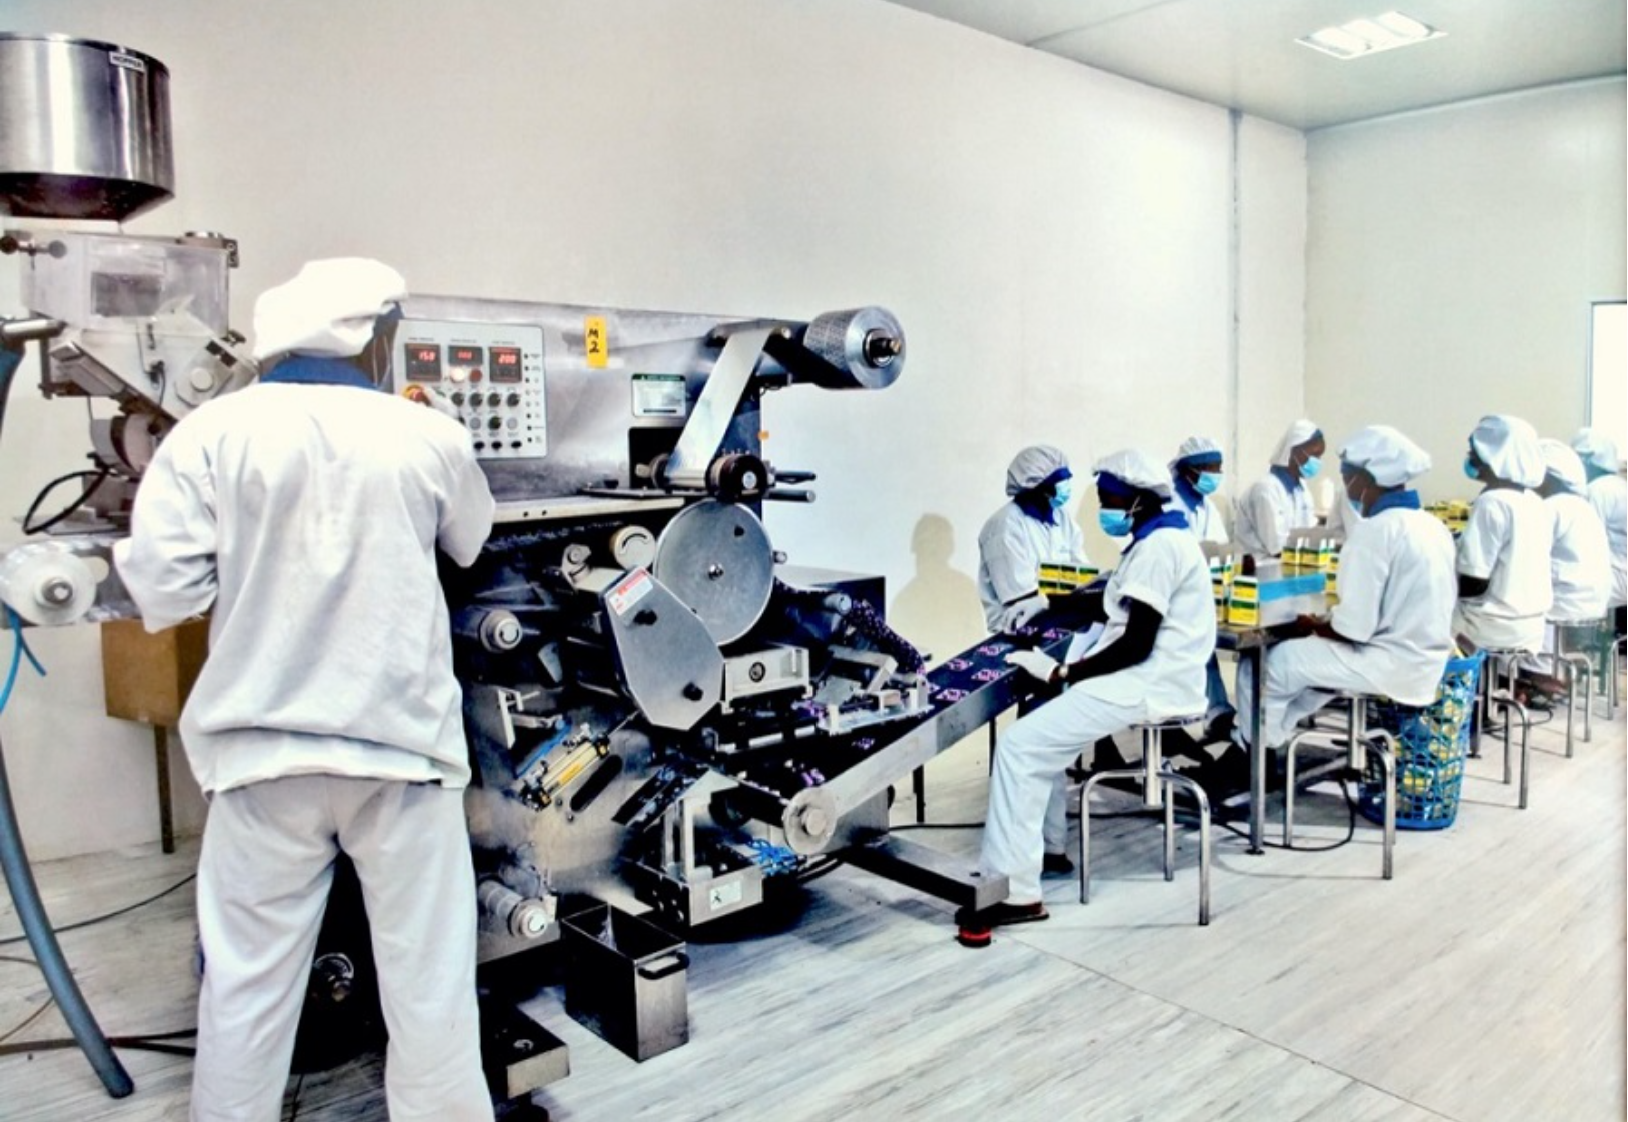
LAGOS, Nigeria — MeCure Industries Plc has opened an offer of up to ₦14 billion in Series 8 commercial paper under its ₦40 billion Commercial Paper Programme. The Lagos-based maker of medicines and multivitamins is raising short-term money for working capital.
The MeCure commercial paper carries an implied annual yield of 21%. An investor who holds it for the full 267-day tenor would earn about 15.36% on the amount invested, before applicable deductions, provided MeCure repays in full.
The offer opened on Wednesday, October 14, 2026 and closes on Tuesday, October 20, 2026.
MeCure commercial paper offer terms
- Programme size: ₦40 billion
- Series 8 target: up to ₦14 billion
- Tenor: 267 days
- Discount rate: 18.2036% per annum
- Gross implied yield: 21% per annum, stated as inclusive of withholding tax
- Allotment date: Tuesday, October 20, 2026
- Settlement date: Wednesday, October 21, 2026
- Maturity date: Thursday, July 15, 2027
- Minimum subscription: ₦5 million, then multiples of ₦1,000
- Ratings stated in the offer: A1 from DataPro and A3 from GCR
- Listing: Nigerian Exchange Limited and/or FMDQ Securities Exchange Limited
The issue follows MeCure’s offer of up to ₦10 billion in Series 7 paper in February 2026, which had a 269-day tenor and a gross annualised yield of 21.75%. The new offer raises the target by ₦4 billion and pays 0.75 percentage points less over a similar period.
Investors buy the paper below its repayment value and receive that value at maturity. On ₦5 million invested, the stated yield would generate about ₦768,000 in gross income over 267 days on a 365-day basis. Total proceeds would be about ₦5.768 million, before applicable deductions and subject to full repayment.
Why the MeCure commercial paper yield stands out
The 21% yield is higher than the 17.16% and 18.91% offered by six-month and one-year Treasury bills at the October 14 auction, though MeCure’s paper runs for a different period. It also stands above September’s inflation rate of 14.63%. The actual benefit will depend on taxes, fees and how inflation moves before repayment.
Kanyi Daily reports that the more important question is whether MeCure can repay. The company announced that it fully repaid its ₦3 billion bond in April 2026, which offers some reassurance.
Repayment capacity behind MeCure commercial paper
MeCure’s revenue rose 20.4% to ₦44.85 billion in H1 2026. Lower marketing expenses helped operating profit grow faster, by 41% to ₦10.90 billion.
Expansion is raising its funding needs. The company invested ₦16.69 billion in facilities and equipment in H1, well above the ₦1.45 billion of cash its operations generated. Borrowing and existing cash covered the gap, leaving ₦2.07 billion in cash at June.
Total borrowings rose 19.6% from December to ₦66.17 billion, about ₦3 borrowed for every ₦1 of shareholders’ funds. Finance costs jumped 54.9% to ₦5.93 billion, absorbing 54% of operating profit against 49% a year earlier. Operating profit still covered the costs, but they took a larger share of earnings.
The new facilities could reverse that trend if they generate enough extra sales and cash to outpace their costs. For investors in the paper, repayment confidence will depend on those cash receipts and on the funding available at maturity.
Risks for MeCure commercial paper investors
The main considerations are rising financing costs, cash committed to expansion and the timing of customer receipts. Further borrowing could absorb part of the benefit from stronger operating earnings, and slower collections or delayed returns from new capacity could raise funding needs.
Investors who sell before maturity may get a different return from the advertised yield. They should confirm their net income after applicable deductions and plan around the July 2027 maturity.